Showing posts with label China. Show all posts

Sunday, December 2, 2012

Bear No More - It's Time To Get Beta In China


The Chinese stock market has had a volatile year, initially rallying before slumping as concerns about a hard landing culminated in speculation on the end of the Chinese economic growth model. If history shows us anything it's that people will always overreact; on the down side and the upside. But is it an overreaction to still be bearish on China?
In order to answer this question, we need to review a number of key economic and market themes. The bottom line is that there is a compelling outlook, but it's not as simple as it may seem.

Monday, June 4, 2012

China Update - Housing Market and Manufacturing


The first bits of data that come out of China each month are the PMI (a measure of manufacturing) and the Soufun 100 Index (a measure of house prices). The housing sector and manufacturing sector remain critical to the near term prospects of China's overall economy and macro policy positioning. So with these two data points you can get a leading view on how China's economy. And what do they say?


Full Story: http://www.alleconomists.com/2012/06/china-update-housing-market-and.html

Tuesday, January 24, 2012

China Economic Update: The Softest of Landings

China recently released its major regular economic data dump, and the results were well, remarkably good. GDP growth tapered off ever so gently, retail sales growth accelerated, industrial production chugged along, fixed asset investment slowed slightly, trade volumes held up, property prices continued a gentle descent, and loan growth showed a cautious but somewhat easier pace, and inflation continued to ease-off. In essence the December data was consistent with a smooth and steady landing, with all the right spots showing the right signs. But where to next? Can we expect a continued pleasant ride, or are we on the cusp of turbulence? And what are the implications for investors?

Full story: http://seekingalpha.com/article/321399-china-economic-update-the-softest-of-landings

Friday, October 21, 2011

China Update: Something For Everyone

China pretty much wrapped up its key economic data releases this week. As always there's plenty of stuff for everyone amongst all the various data-points and sources. So this article attempts to digest some of the data and figure out what it means for the near and medium term outlooks for China's economy and markets.

Saturday, October 8, 2011

China Property Update - What's going on?

Just a quick update on the Chinese property market. I tend to keep one eye on the Soufun 100-city index, and the other eye on the NBS 70-city data. Of course it is somewhat fraught to look at an aggregated-up index over such a vast and diverse country, but the trend is still very important for macro analysis of China given the strong link of fixed asset investment, government revenue, private wealth, and of course the banking and finance sector to real estate prices and activity.

So in this update I'll show you the Soufun graphs with the September data, and pop in a few other relevant bits and pieces I've happened upon.

First Glance: I have been expecting a gradual turnaround in real estate prices; and slower gains are now looking to be turning into small losses. A key question, and a key risk area for China, will be the extent to which the property market slows. A route in prices wont be the end of China but it will mark a temporary end to its post-bubble-government-reflation-bubble.

So, onto the Soufun (maybe not 'so-fun'?) data. In September prices fell a whopping -0.03% to an average 8,877 yuan per square meter. The current level is 313 yuan higher than the start of the year, and up about 6.1% from the same time last year.
Prices rose in 54 out of 100 cities, and fell in 44 cities (2 unch). The last point is noticeable - the graph below charts the no. of cities which recorded rising prices, and yes, that does look like a trend.
So, the Soufun data so looks like the start of a trend, but of course we'll need to see another couple of months before we can rule out fluctuations. Also the NBS data will be out - usually around the 18/19th of the month, so it will be good to check that dataset for confirmation.

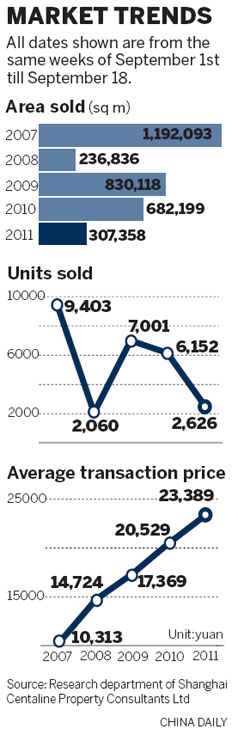
Now, onto another couple of charts I found in a China Daily article. The data in the charts are for 1-18 Sep in the relevant years. Key points: volume has tanked compared to levels seen during the the pre-2008 bubble, and the post-2008 reflation bubble. Prices have doubled over 5 years (but then incomes have also doubled over the past 5 years).
If you saw a stock chart with a surging price, and with volume which trailed off to low levels, what would you think? The answer has to be that the market is getting a bit fatigued at the current price level. But having said that, I still think there are fundamental forces which should logically support higher prices (e.g. urbanization, rising incomes, the culture part of needing to own a house, demand for property as a store of value/inflation hedge, etc).

The dual forces of price exhaustion and government policy aimed at improving house price affordability, will likely continue to weigh on property prices in the near term though. I struggle to see a catastrophic unwinding, rather a period of price dullness; with the market naturally taking a breather, and the government breathing down the neck of developers and bankers.

To me it seems there is enough fundamental strength to support a baseline demand and price level for property in China. But like many, I am paying a lot of attention to the "landing" of China, and whether it be soft, hard or something in between. In any case the market will be pricing (or overpricing) any further signs of a harder landing, or more relevantly - the likelihood of the formation of perfect storms; and that is a non-zero probability risk.

Proceed with caution (and optimism).

Econ Grapher

Saturday, July 16, 2011

China Economic Check-up: Nope, no hard landing yet folks

China just released its June numbers, with 3 separate official sources delivering banking and money stats, international trade stats, and the core economic data. The June GDP numbers were pretty strong in the scheme of things, and the rest of the data pointed to a high likelihood of persistence in economic strength, at least in the medium term. In this article we explore some of the key data points, and come to the conclusion that a hard landing/significant slow down is a not a 2011 story...

1. China GDP
China managed to show year on year GDP growth of 9.5% in the June quarter, which was slightly lower than the 9.7% it showed in the previous quarter and 10.3% in June 2010, and compares to a 10-year average of about 9.4%. So in the scheme of things GDP growth does not show a significant degree of slowing. However, if you redefined recession for China as passing below the long term average growth rate - rather than descending into the negatives, then China could dip just below that line later this year. So, in spite of a succession of tightening moves, e.g. the PBOC raised interest rates earlier this month, growth has not yet taken a hit, and it makes sense because the dual forces of strong underlying fundamentals as well as strong sources of manufactured growth e.g. social housing, persist - so sorry folks, no slow down or hard landing in 2011.

2. China inflation
But one area that persists as a weak-point or vulnerability is the surging inflation numbers. Inflation hit 6.4% in June (I was expecting about 6.5%), with most of that coming from food price inflation (14.4%), and non-food static around 3%. This remains a risk because if it gets out of control then it poses stability risks, but more importantly, persistently high and rising inflation will put pressure on policy makers to tighten the screws further on monetary policy - that could slow things down a bit more, and certainly put some headwinds in front of Chinese equities. But I'm seeing signs that this could be the peak - there are a few people out there that have been forever calling the peak - but things like a turn in the prices index part of the PMI, the tightening done to date, and market responses to high prices. The Yuan could be worked harder to achieve lower inflation outcomes, but it's no silver bullet either. I see inflation as a risk, but I can see a scenario where inflation starts to taper off.

3. PMI and Industrial Production
The industrial production figure was a slight surprise in that it broke from where the PMI suggested it should go. The figure came in at 15.1% y/y, up from 13.3% in May, 13.7% in June 2010. The official PMI dropped to 50.9 for June, from 52 in the previous month - this is one of the main areas that people have been pointing to for signs of a slowdown, and fair enough - new orders have trailed off , but still above the expansionary 50 point mark. So it's mixed signals from this one, July will tell if June was a quirk or a sign that the bottom has been hit on the slowing in industrial production growth - so watch this space.

4. International Trade
China reported another record month for exports, 162B for June, while imports trailed off some to 139.7B (high of 152B in March). So what are the messages from the trade results?, first off, net exports were positive for the quarter (about 47B vs 0 in the March quarter), so there was a decent positive GDP contribution from trade during June. So the upward trend in exports are a positive sign for China's economy, but also indicate a certain degree of strength in global demand, on the imports side, it almost sends a signal of lower import demand, some of this may be related to a tapering off in commodity prices, but it is something to keep an eye on.

5. New Loans
New loans in China has been the gasoline that has been fueling the heat in the property market, as well as wider influences such as inflation and general growth. There has been a range of moves designed to cap lending growth (including RRR hikes and tougher lending rules), but new loans are still going strong, YTD new loans are about 4 trillion yuan (about 5 trillion in H1 2010, and close to 8 trillion in H1 2009). It's no secret that this rapid expansion in lending is a risk area, and a lot of China bears have been pointing to this, as well as the local government debt issues. A lot of water needs to go under the bridge and a lot of info needs to come to light before the full view of what's really going on in China's property and lending markets come into full light, but for now, the still elevated rate of loan growth remains stimulatory for both the economy and property prices (also note on property prices, real income per capita rose about 7.6% in June y/y, compared to property prices about 5-6% y/y).

Summary

So, as always it was interesting to digest all the info in the June economic data reports from China. The high level view is that China's economy is still going strong, it is strong in many areas, and appears to have broad fundamental strength. Aside from fundamental strength China's economy is also boosted by expansionary policies such as the 10 million unit social housing project for this year - which will be loaded mostly in H2 in terms of construction starts. But aside from stimulatory polices and broad based strength, there are inevitably risk areas too, such as the overheating and inflation risks, the property market risks, and the local government debt risks. Evidence points to none of these coming squarely home to roost in 2011. If there's a slow down coming in China, it's a 2012 or 2013 story - so, no hard landing yet folks!

Sources
1. National Statistics Bureau www.stats.gov.cn
2. National Statistics Bureau www.stats.gov.cn
3. CFLP www.chinawuliu.com.cn & Markit/HSBC www.markiteconomics.com & National Bureau of Statistics www.stats.gov.cn
4. China Customs www.customs.gov.cn
5. People's Bank of China www.pbc.gov.cn

Monday, June 13, 2011

Economic Calendar: China Data and Developed Market Inflation

Here's the economic calendar for the week commencing the 12th of June 2011. This week the main event is China’s monthly data dump, where it will release CPI, PPI, retail sales, industrial production, new loans, money supply, and fixed asset investment figures. Speaking of inflation data, the US, UK, and EU all also have inflation data due out this week. Also, Japan, Switzerland, and India are among the central banks announcing interest rate decisions this week.

Date

GMT

Country/ Currency

Event

Forecast

Previous

SUN

CNY

Actual FDI (YoY)

15.20%

SUN

NZD

REINZ House Sales (YoY)

-4.20%

SUN

CNY

New Yuan Loans

650.0B

739.6B

SUN

CNY

Money Supply - M0 (YoY)

14.70%

SUN

CNY

Money Supply - M1 (YoY)

13.70%

12.90%

SUN

CNY

Money Supply - M2 (YoY)

15.50%

15.30%

SUN

23:50

JPY

Machine Orders (YoY)

4.90%

9.10%

MON

08:00

EUR

Italian Industrial Production n.s.a. (YoY)

2.00%

0.80%

MON

JPY

Bank of Japan Rate Decision

0.10%

0.10%

MON

00:01

CNY

China Manpower Survey

29.00%

MON

02:00

CNY

Producer Price Index (YoY)

6.50%

6.80%

MON

02:00

CNY

Consumer Price Index (YoY)

5.50%

5.30%

MON

02:00

CNY

Retail Sales (YoY)

17.00%

17.10%

MON

02:00

CNY

Retail Sales YTD YoY

16.90%

16.50%

MON

02:00

CNY

Industrial Production (YoY)

13.10%

13.40%

MON

02:00

CNY

Industrial Production YTD YoY

14.00%

14.20%

MON

02:00

CNY

Fixed Assets Inv Excl. Rural YTD YoY

25.20%

25.40%

TUE

04:30

JPY

Industrial Production (YoY)

-14.00%

TUE

08:30

GBP

Consumer Price Index (YoY)

4.50%

4.50%

TUE

08:30

GBP

Core Consumer Price Index (YoY)

3.50%

3.70%

TUE

08:30

GBP

Retail Price Index (YoY)

5.20%

5.20%

TUE

12:30

USD

Producer Price Index (YoY)

6.60%

6.80%

TUE

12:30

USD

Producer Price Index Ex Food & Energy (YoY)

2.10%

2.10%

TUE

12:30

USD

Advance Retail Sales

-0.40%

0.50%

TUE

12:30

USD

Retail Sales Less Autos

0.30%

0.60%

TUE

12:30

USD

Retail Sales Ex Auto & Gas

0.30%

0.20%

WED

05:30

EUR

French Consumer Price Index (YoY)

2.10%

2.10%

WED

07:15

CHF

Producer & Import Prices (YoY)

-0.10%

0.10%

WED

08:30

GBP

Jobless Claims Change

6.5K

12.4K

WED

09:00

EUR

Euro-Zone Industrial Production w.d.a. (YoY)

4.80%

5.60%

WED

12:30

USD

Consumer Price Index (YoY)

3.40%

3.20%

WED

12:30

USD

Consumer Price Index Ex Food & Energy (YoY)

1.40%

1.30%

WED

13:15

USD

Industrial Production

0.20%

0.00%

WED

13:15

USD

Capacity Utilization

77.00%

76.90%

WED

22:00

NZD

Westpac NZ Consumer Confidence

97.90

WED

02:00

CNY

China April Leading Economic Index

THU

07:15

CHF

Industrial Production (YoY)

5.60%

6.10%

THU

07:30

CHF

Swiss National Bank Rate Decision

0.25%

0.25%

THU

08:00

EUR

Italian Consumer Price Index (YoY)

3.00%

3.00%

THU

08:30

GBP

Retail Sales (YoY)

1.50%

2.80%

THU

08:30

GBP

Retail Sales w/Auto Fuel (YoY)

1.50%

2.80%

THU

09:00

EUR

Euro-Zone Consumer Price Index - Core (YoY)

1.60%

1.60%

THU

09:00

EUR

Euro-Zone Consumer Price Index (YoY)

2.70%

THU

09:00

EUR

Euro-Zone Employment (QoQ)

0.20%

THU

09:00

EUR

Euro-Zone Employment (YoY)

0.20%

THU

12:30

USD

Building Permits

552K

563K

THU

12:30

USD

Housing Starts

545K

523K

THU

12:30

USD

Current Account Balance

-$130.0B

-$113.3B

THU

23:50

JPY

BOJ Minutes of May 19-20 Board Meeting

FRI

09:00

EUR

Euro-Zone Construction Output w.d.a. (YoY)

-4.90%

FRI

13:55

USD

U. of Michigan Confidence

74.00

74.30

As noted the main event this week will be the China data, which is always good to check up on to gauge how the world’s second largest economy is tracking. One of the key indicators to watch will be inflation, i.e. CPI, which is expected to show a slightly higher year on year rate, about 5.8% as property expenses and food prices have been tracking upwards in May. The other data points; industrial production, retail sales, and fixed asset investment should come in more or less flat, but watch for any significant changes or extension of slowing in some of the points.


Another key data set will be the inflation numbers. The United States is expected to show a slight increase in both headline and core inflation, with year on year CPI inflation expected around 3.4%. The UK is expected to see a slight slowing of its core inflation rate and headline should stay around 4.5%. The Euro Zone will likely see headline inflation stick around 2.7% and core about 1.6%. So, not expecting anything dramatic, but a slight upward tick in inflation.


In the monetary policy space there’s the Bank of Japan on the 14th of June (expected to hold at 0.10%), Central Bank of Chile on the 14th of June (expected to raise 25bps from current 5.00%), Central Bank of Iceland on the 15th of June (expected to hold at 4.25%), Central Bank of Philippines on the 16th of June (expected to raise 25bps from current 4.50%), the Reserve Bank of India on the 16th of June (expected to raise 25bps from current 7.25%), and The Swiss National bank also on the 16th (expected to hold at 0.25%). Of course there is also a chance the People's Bank of China will do something when the inflation figures come out.


Elsewhere there’s some key US data points to watch: Producer prices are expected to show little change, retail sales are expected to decline – but post a small gain excluding autos, industrial production may show a small gain, while the UoM confidence index should stay around 74. Outside of the US, Japan has machine orders and industrial production figures, and the Euro Zone has some employment numbers.


So as always, have a great week, watch out for surprises, and stay tuned for updates...

Sources

· DailyFX

· Forex Pros

· Forex Factory

· Bloomberg

+various statistics websites and central bank websites for verificatio